Home Loan Refinancing in Melbourne
Refinancing & Rate Reviews
Reviewed by Brendan Singh, Mortgage Broker (Credit Rep 575816) · Last reviewed October 2026
Is your current home loan still the best deal? We'll review your loan and find options that could reduce your repayments, depending on your loan and lender. No obligation, no pressure.
Why Refinance Your Home Loan?
Refinancing isn't just about getting a lower rate. It's about aligning your loan with your current financial goals and circumstances.
Lower Interest Rates
Access competitive rates that could reduce your repayments, depending on your loan and lender.
Access Equity
Unlock your home equity for renovations, investments, or other financial goals.
Consolidate Debt
Roll multiple debts into one manageable payment with potentially lower interest.
Is Refinancing Right For You?
Our Refinancing Process
Free Rate Review
We review your current loan and compare it against products from our panel of 30+ lenders.
Options Presentation
We present you with clear options, showing potential savings and any costs involved in switching.
Application Support
If you decide to proceed, we handle the application process and liaise with your new lender.
Settlement & Beyond
We manage the settlement process and remain available for ongoing support.
"We refinanced with Brendan and couldn't be happier. He found us a better deal than our bank offered and handled all the paperwork."
— Rajiv M., Google Review
"Extremely prompt, paid great attention to detail, and presented clear options tailored to my situation."
— E. Khera, Google Review
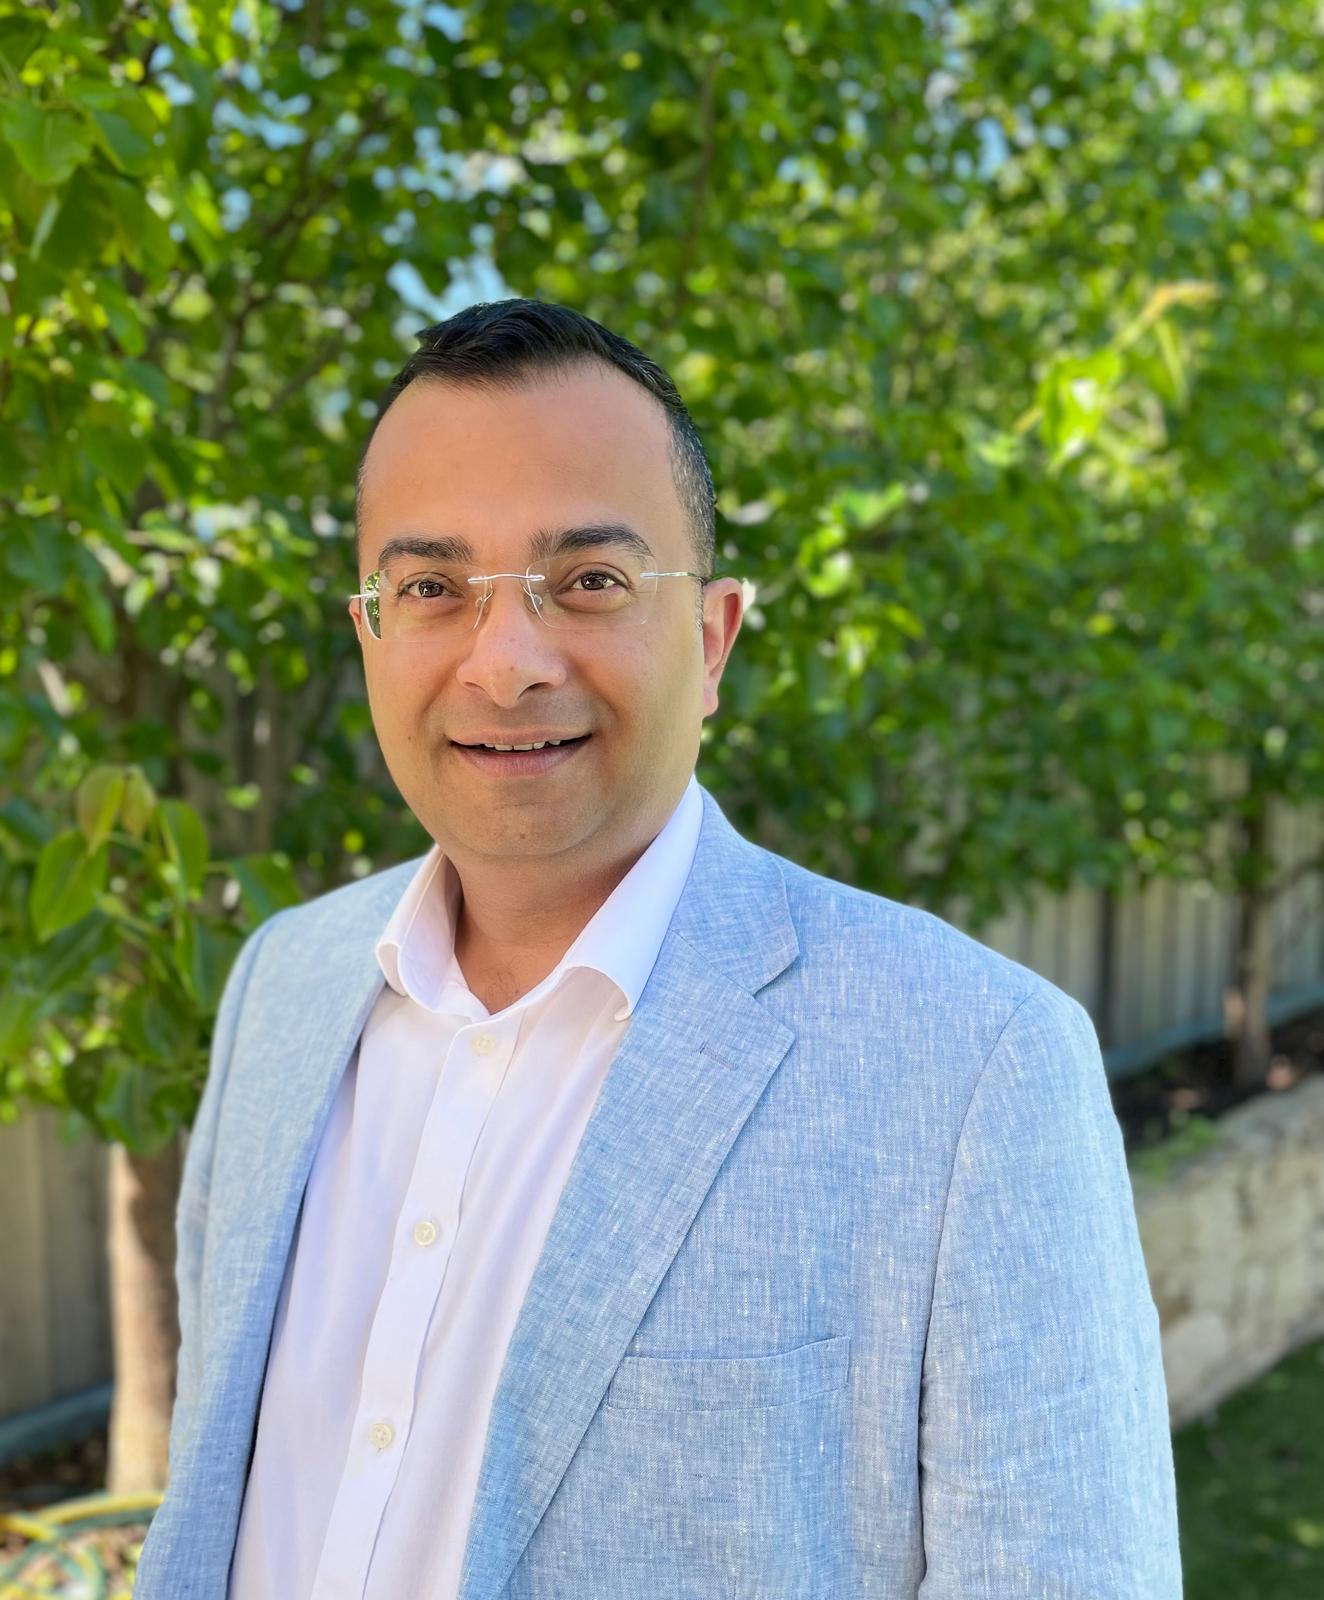
You'll be working with:
Brendan Singh — Director & Mortgage Broker
Credit Rep 575816 | ACL 391209 | 30+ lenders
English · Hindi · Punjabi
View profileGet Your Free Rate Review
Fill out the form below and we'll review your options within 24 hours on business days.
Refinancing questions — answered
How do I know if I should refinance my home loan?
The most common trigger is a gap between your current interest rate and what's available on the market — even a 0.5% difference on a $600,000 loan can mean a significant difference in monthly repayments over time. Other good reasons to refinance include accessing equity in your property, consolidating debts, switching from a variable rate to a fixed rate, or moving from an interest-only loan to principal and interest. At Loans Cart, we review your existing loan against our 30+ lender panel at no charge and give you a straight answer on whether refinancing makes financial sense in your situation.
How much does it cost to refinance a home loan?
The usual costs are a discharge fee from your current lender, government fees to register the new mortgage, and any setup fees from the new lender. Fixed-rate loans can also have break costs. Loans Cart works out the total before you decide, so you can compare it with what you'd save.
Can I refinance if my loan is on a fixed rate?
Yes, but breaking a fixed rate early can mean a break cost, which can be large. It's often better to plan a refinance for when the fixed period ends. We can check the likely cost with your lender first.
Can I access equity when I refinance?
Usually. If your home has gone up in value, you may be able to borrow more for renovations, an investment property or other purposes, typically up to 80% of its value without LMI. The new loan still has to fit your income.
Will refinancing affect my credit score?
A little. Each application creates a credit enquiry on your file. That's why we compare lenders first and submit one application to the lender that fits, rather than applying to several.
Do you offer cashback when I refinance?
Minimum $500 cashback available — conditions apply (minimum loan $550,000, selected lenders, paid after settlement).
How long does refinancing take?
From your initial consultation to settlement, a straightforward refinance typically takes 3 to 4 weeks for a straightforward refinance. This includes comparing lenders, submitting your application, formal approval, and the discharge of your existing loan. More complex situations — self-employed borrowers, unusual security properties, or high LVR loans — can take longer. At Loans Cart, we manage the process from start to finish, including chasing the lender and coordinating the discharge with your existing bank.
Can I refinance if I'm self-employed?
Yes, but lenders assess self-employed income differently, so the process and lender options are different. Most lenders want to see two years of tax returns and business financials, though some specialist lenders offer low-documentation loans for borrowers with a shorter self-employment history. Loans Cart regularly works with self-employed clients and has access to lenders who are experienced with ABN income, sole trader structures, and business owner situations.
Learn more about self-employed lendingHow often should I review my home loan?
A general rule of thumb is to review your home loan every two years, or any time there's a significant change in your circumstances — a pay rise, a change in property value, or a shift in the interest rate environment. Lenders regularly offer sharper rates to new customers than they do to existing ones, which means long-term borrowers can end up paying more than necessary simply through loyalty. Loans Cart offers free rate reviews at any time — book a call and we'll tell you where you stand.
Can a mortgage broker in Melbourne help me refinance a property in another state?
Yes. Loans Cart is based in Mount Waverley, Melbourne, but services clients and properties Australia-wide. Refinancing a property in another state is handled the same way as a local refinance — the lender, valuation, and discharge process differ by state, but the broker's role is identical. Consultations are available in person at the Mount Waverley office or online via video call.