First Home Buyer Mortgage Broker Melbourne
Your First Home in Melbourne — Let's Make It Happen
Reviewed by Brendan Singh, Mortgage Broker (Credit Rep 575816) · Last reviewed October 2026
Buying your first home is one of the biggest decisions you'll make. It can feel overwhelming — the deposit, the grants, the lenders, the process. We cut through the complexity and walk you through every step, in plain English.
What's Actually Involved in Buying Your First Home
Most first home buyers don't know what they don't know. Here's what the process actually looks like — and where we help at every stage.
Work out your borrowing capacity
Before you look at a single property, you need to know your number. We look at your income, expenses, deposit, and any government schemes you qualify for — and give you a realistic ceiling before you start searching.
Get pre-approved
Pre-approval is a written indication from a lender that they'll lend you up to a certain amount. In Melbourne's market, making an offer without pre-approval puts you at a disadvantage. We get you pre-approved — typically within 24–72 hours — so you can move quickly when you find the right property.
Understand your grants and schemes
There's real government money available for first home buyers in Victoria. We identify exactly what you're eligible for before you apply for anything.
Find your property and make an offer
Once you have pre-approval and a clear budget, you can search with confidence. When you find the right property and your offer is accepted, we move to formal approval.
Formal approval and settlement
We handle the lender communication, manage the paperwork, and coordinate with your conveyancer through to settlement. You get the keys — we handle everything behind the scenes.
Victorian Government Grants & Schemes — What You Could Access
First Home Owner Grant (FHOG)
Up to $10,000 for eligible first home buyers purchasing or building a new home valued at $750,000 or less. Available for new builds only — not established homes.
Stamp Duty — Full Exemption or Concession
In Victoria, first home buyers pay no stamp duty on properties valued up to $600,000. For properties between $600,001 and $750,000, a concessional rate applies — saving you tens of thousands compared to a standard purchase. Properties over $750,000 attract full stamp duty.
5% Deposit Scheme (Federal Government)
The Australian Government 5% Deposit Scheme lets eligible buyers purchase with a 5% deposit and no Lenders Mortgage Insurance. There are no income caps and no limit on places. The price cap is $950,000 in Melbourne and Geelong, and $650,000 in the rest of Victoria.
Learn more about the 5% Deposit SchemeRegional Victoria Buyers
Buying in regional Victoria? Regional buyers use the same 5% Deposit Scheme, with a $650,000 price cap outside Melbourne and Geelong.
First Home Super Saver Scheme (FHSS)
Allows you to make voluntary contributions into your superannuation fund and withdraw them (plus earnings) for a first home deposit. Contributions are taxed at a lower rate inside super, which can accelerate your deposit savings.
Note: Eligibility conditions apply to all schemes. Income thresholds, property price caps, and first home buyer status requirements vary. Loans Cart will assess what you're actually eligible for based on your situation — before you apply for anything.
How Much Deposit Do You Actually Need?
The standard answer is 20% — but most first home buyers don't need that much.
With the First Home Guarantee, eligible buyers can purchase with as little as 5% deposit without paying Lenders Mortgage Insurance. Without that scheme, a deposit below 20% typically attracts LMI, which can add thousands to your loan.
On top of your deposit, budget for purchase costs — stamp duty (unless exempt), conveyancing fees ($1,500–$2,500), building and pest inspection ($400–$700), and any loan establishment fees. For most first home buyers in Victoria, total upfront costs beyond the deposit are in the range of 2%–5% of the purchase price.
Brendan will work through your exact deposit position and purchase costs based on the price range you're targeting — before you start looking at properties.
Why First Home Buyers Use a Broker
A bank can only show you its own products. Loans Cart compares options across 30+ lenders — including lenders whose policies on deposit requirements, government scheme eligibility, and income assessment are more flexible than the major banks.
For first home buyers, this matters because:
- •Different lenders assess your income differently — especially if you're casual, contract, or recently started a new job
- •Eligibility for the First Home Guarantee must be applied through a participating lender — we know which ones process applications fastest
- •LMI costs vary significantly between lenders — we find the lowest cost option for your deposit size
- •We handle all the paperwork and lender communication — so you're not chasing anyone
There is no cost to you for using Loans Cart. We are paid a commission by the lender after your loan settles, and we are required by law to recommend what suits you — not what pays us the most.
We Speak Your Language
Brendan Singh at Loans Cart is fluent in English, Hindi, and Punjabi. If you'd prefer to discuss your first home purchase in Hindi or Punjabi, appointments are available in person at our Truganina office (Suite 6/45 Tallis Circuit) or Mount Waverley office (Unit 5/15 Ricketts Rd) — or online, whichever suits you.
First Home Buyer Questions — Answered
How much deposit do I need to buy my first home in Victoria?
With the 5% Deposit Scheme you can buy with a 5% deposit and no LMI. Eligible single parents may buy with 2% through the Family Home Guarantee. Without a scheme, most lenders want 10–20%, and LMI usually applies under 20%.
What grants are available for first home buyers in Victoria in 2026?
Victorian first home buyers may be eligible for the First Home Owner Grant ($10,000 for new builds up to $750,000), stamp duty exemption for properties up to $600,000 (concessional rate to $750,000), the First Home Guarantee (5% deposit, no LMI, income and price caps apply), and the First Home Super Saver Scheme. Eligibility varies — Loans Cart assesses what you actually qualify for before you apply.
What is pre-approval and do I need it?
Pre-approval is a lender's written indication that they'll lend you up to a certain amount, subject to valuation and final document checks. You don't legally need it before inspecting properties, but in Melbourne's market it's strongly advisable — it tells you your real ceiling, makes you a credible buyer, and speeds up formal approval once your offer is accepted. Loans Cart gets most first home buyers pre-approved within 24–72 hours.
How long does the first home buying process take from start to settlement?
The full timeline from initial consultation to settlement is typically 8–12 weeks for a first home purchase. Pre-approval takes 24–72 hours. Formal approval after signing a contract of sale takes 3–7 business days. Settlement occurs on the agreed date in the contract — usually 30–60 days after signing. Loans Cart manages the process end to end and keeps you updated at every stage.
Is it better to use a broker or go directly to my bank?
A broker compares options across a panel of lenders rather than presenting one bank's products. For first home buyers especially, this matters — different lenders have different policies on deposit requirements, LMI, government scheme eligibility, and income assessment. Loans Cart has access to 30+ lenders and will find the option that suits your deposit, income, and timeline. There is no cost to you — we're paid by the lender after settlement.
What if I'm on a casual or contract income?
Casual and contract income is assessed differently by different lenders — some require 12 months of history in the same role, others are more flexible. Loans Cart knows which lenders on our panel are most accommodating for non-standard employment and will match you to the right one based on your situation.
Can I use a broker who speaks Hindi or Punjabi?
Yes. Brendan Singh at Loans Cart is fluent in English, Hindi, and Punjabi. If you'd prefer to discuss your first home purchase in Hindi or Punjabi, in-person appointments are available at our Mount Waverley office or online.
Do I need a conveyancer or solicitor as well as a broker?
Yes — a broker handles the loan, a conveyancer or solicitor handles the legal side of the property transfer. The two work in parallel. Loans Cart can refer you to conveyancers we work with regularly if you don't already have one.
Can I combine the First Home Owner Grant, stamp duty relief and the 5% Deposit Scheme?
Yes, if you meet each scheme's rules. A first home buyer building a new home under $600,000 in Melbourne could use all three: a 5% deposit with no LMI, no stamp duty, and a $10,000 grant. Above $600,000 the stamp duty relief reduces, and it ends at $750,000, along with the grant.
Can I use my super to save for a deposit?
Possibly, through the First Home Super Saver Scheme. You make voluntary contributions to super and later withdraw them, with earnings, for a deposit. Up to $15,000 of contributions a year and $50,000 in total count towards it. Get tax advice before you start.
Do I need a 20% deposit to avoid LMI?
Not always. Eligible first home buyers can avoid LMI with a 5% deposit under the 5% Deposit Scheme, and single parents with 2%. A family guarantee is another way to borrow without a 20% deposit or LMI.
"Brendan got me approval in one day. Highly professional and highly recommended."
— Kamal K., Google Review
"Clear communication, proactive and professional — and always a very positive result."
— Nitin V., Google Review
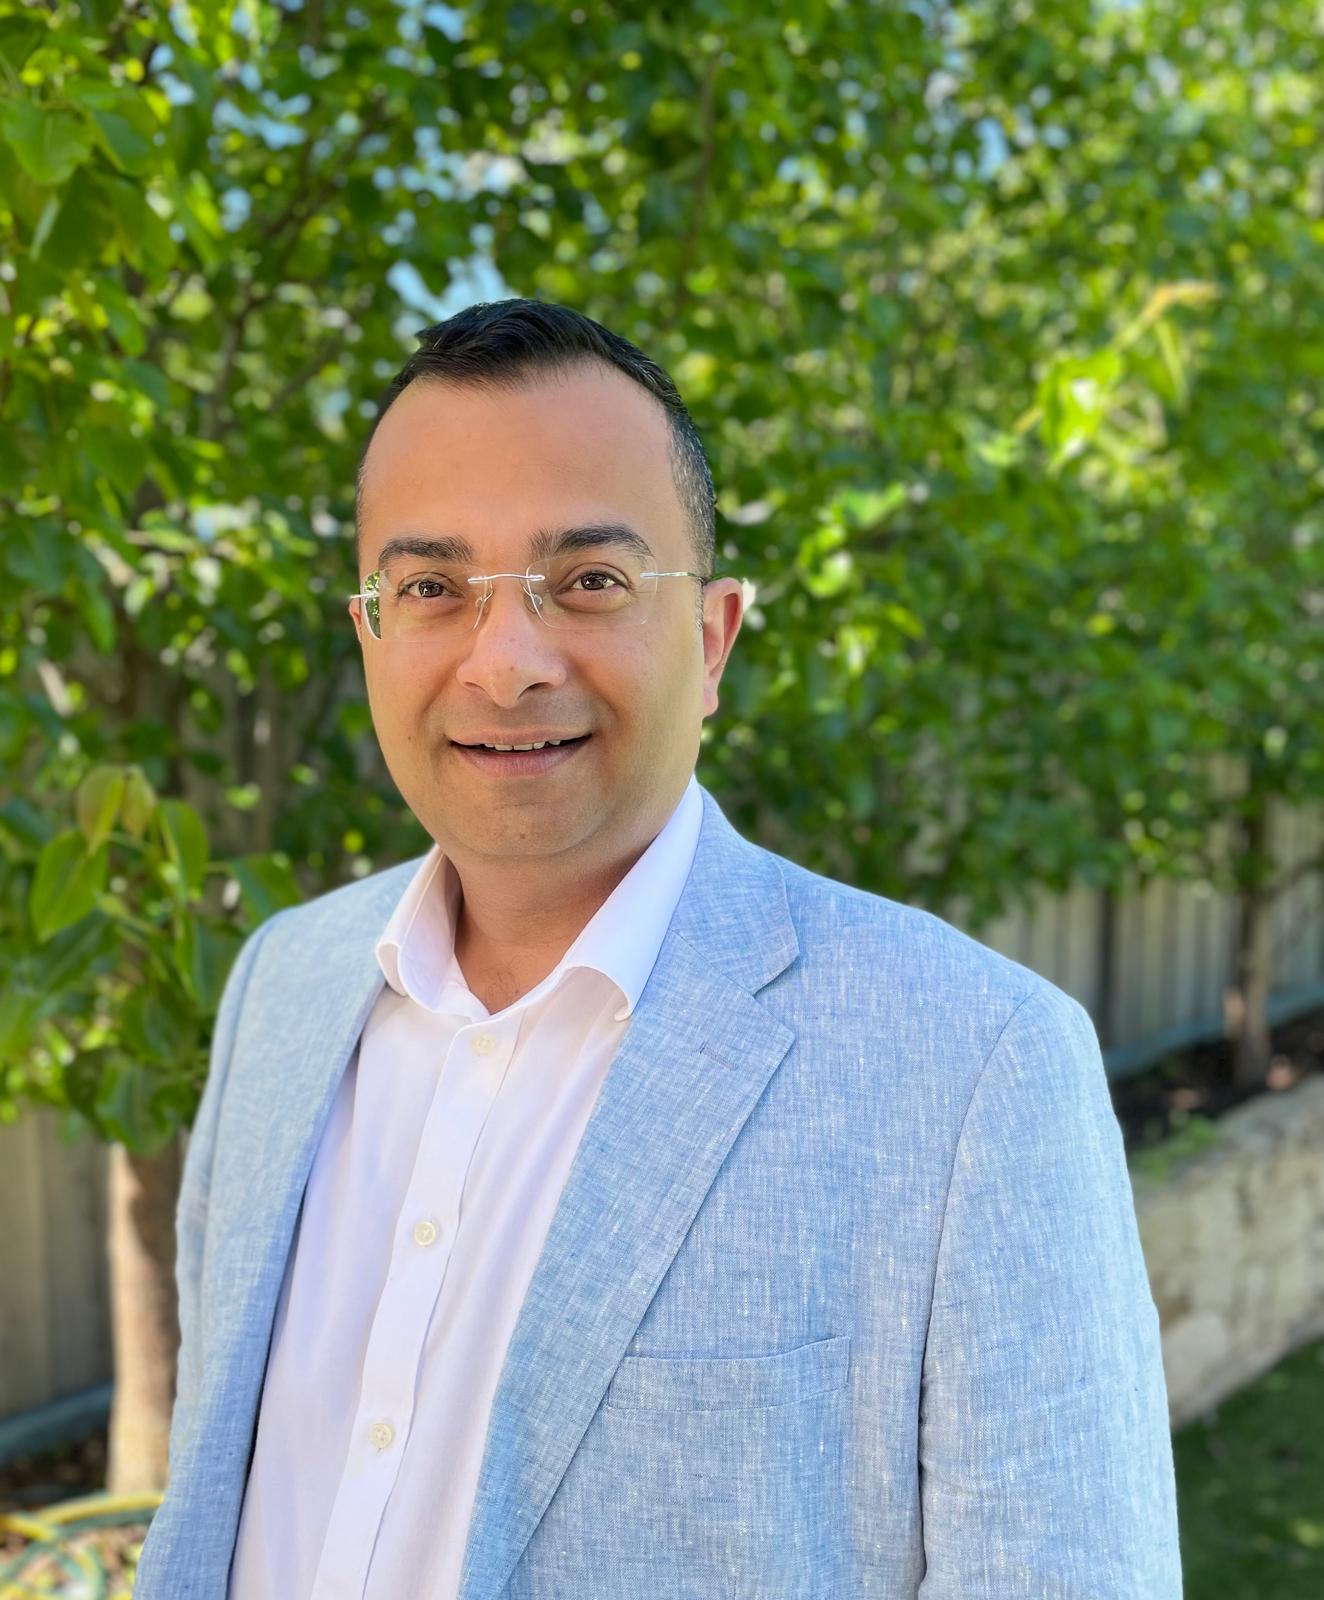
You'll be working with:
Brendan Singh — Director & Mortgage Broker
Credit Rep 575816 | ACL 391209 | 30+ lenders
English · Hindi · Punjabi
View profileStart Your First Home Journey
Let us know a bit about your situation and we'll get back to you with guidance on your next steps.
Ready to Find Out What You Can Borrow?
Book a no-obligation chat with Brendan. We'll look at your deposit, income and situation, tell you exactly what you're eligible for, and map out the steps to get you into your first home.