Why Use a Mortgage Broker?
More than 70% of new home loans in Australia now go through mortgage brokers. Here's why — and what it means for you.
A Broker vs Going Directly to Your Bank
When you go directly to a bank, you see one lender's products. The bank's job is to sell you their loan — not find you the best one for your situation.
A mortgage broker works across multiple lenders. Loans Cart has access to 30+ lenders including major banks, regional banks, building societies, and specialist non-bank lenders. Our job is to compare them and recommend the one that suits you — and we're legally required to do so under the Best Interests Duty.
Going to a Bank
- •One lender's products only
- •Bank's goal is to sell their loan
- •You handle all paperwork and follow-up
- •No Best Interests Duty
Using a Broker
- 30+ lenders compared
- Broker finds the best match for you
- Broker handles all paperwork and lender liaison
- Legal Best Interests Duty applies
What Does a Mortgage Broker Actually Do?
What Does It Cost?
Nothing.
Mortgage brokers in Australia are paid a commission by the lender after your loan settles. There is no upfront fee, no advice fee, and no charge to you at any point.
Loans Cart discloses all commissions as required by law, and our recommendation must be in your best interests — not based on which lender pays us more.
Zero cost to you. Lenders pay us after your loan settles — the same whether you use a broker or go directly to the bank. You get expert advice and lender comparison at no charge.
The Best Interests Duty
Since 2021, mortgage brokers in Australia have been legally required to act in the best interests of their clients. This means the loan we recommend must suit your situation, goals, and financial position — even if another loan would pay us a higher commission.
This duty doesn't apply when you go directly to a bank.
In practice: If Lender A pays us more commission but Lender B is a better fit for your situation, we're legally required to recommend Lender B. This is audited and enforceable under Australian law.
When a Broker Is Particularly Valuable
First home buyers
Navigating grants, deposit requirements, and an unfamiliar process
Self-employed borrowers
Whose income is assessed differently by different lenders
Refinancers
Who want to compare the full market rather than just negotiate with their existing bank
Property investors
Structuring lending across multiple properties
Complex situations
Bad credit, unusual income, non-standard security
Why Choose Loans Cart?
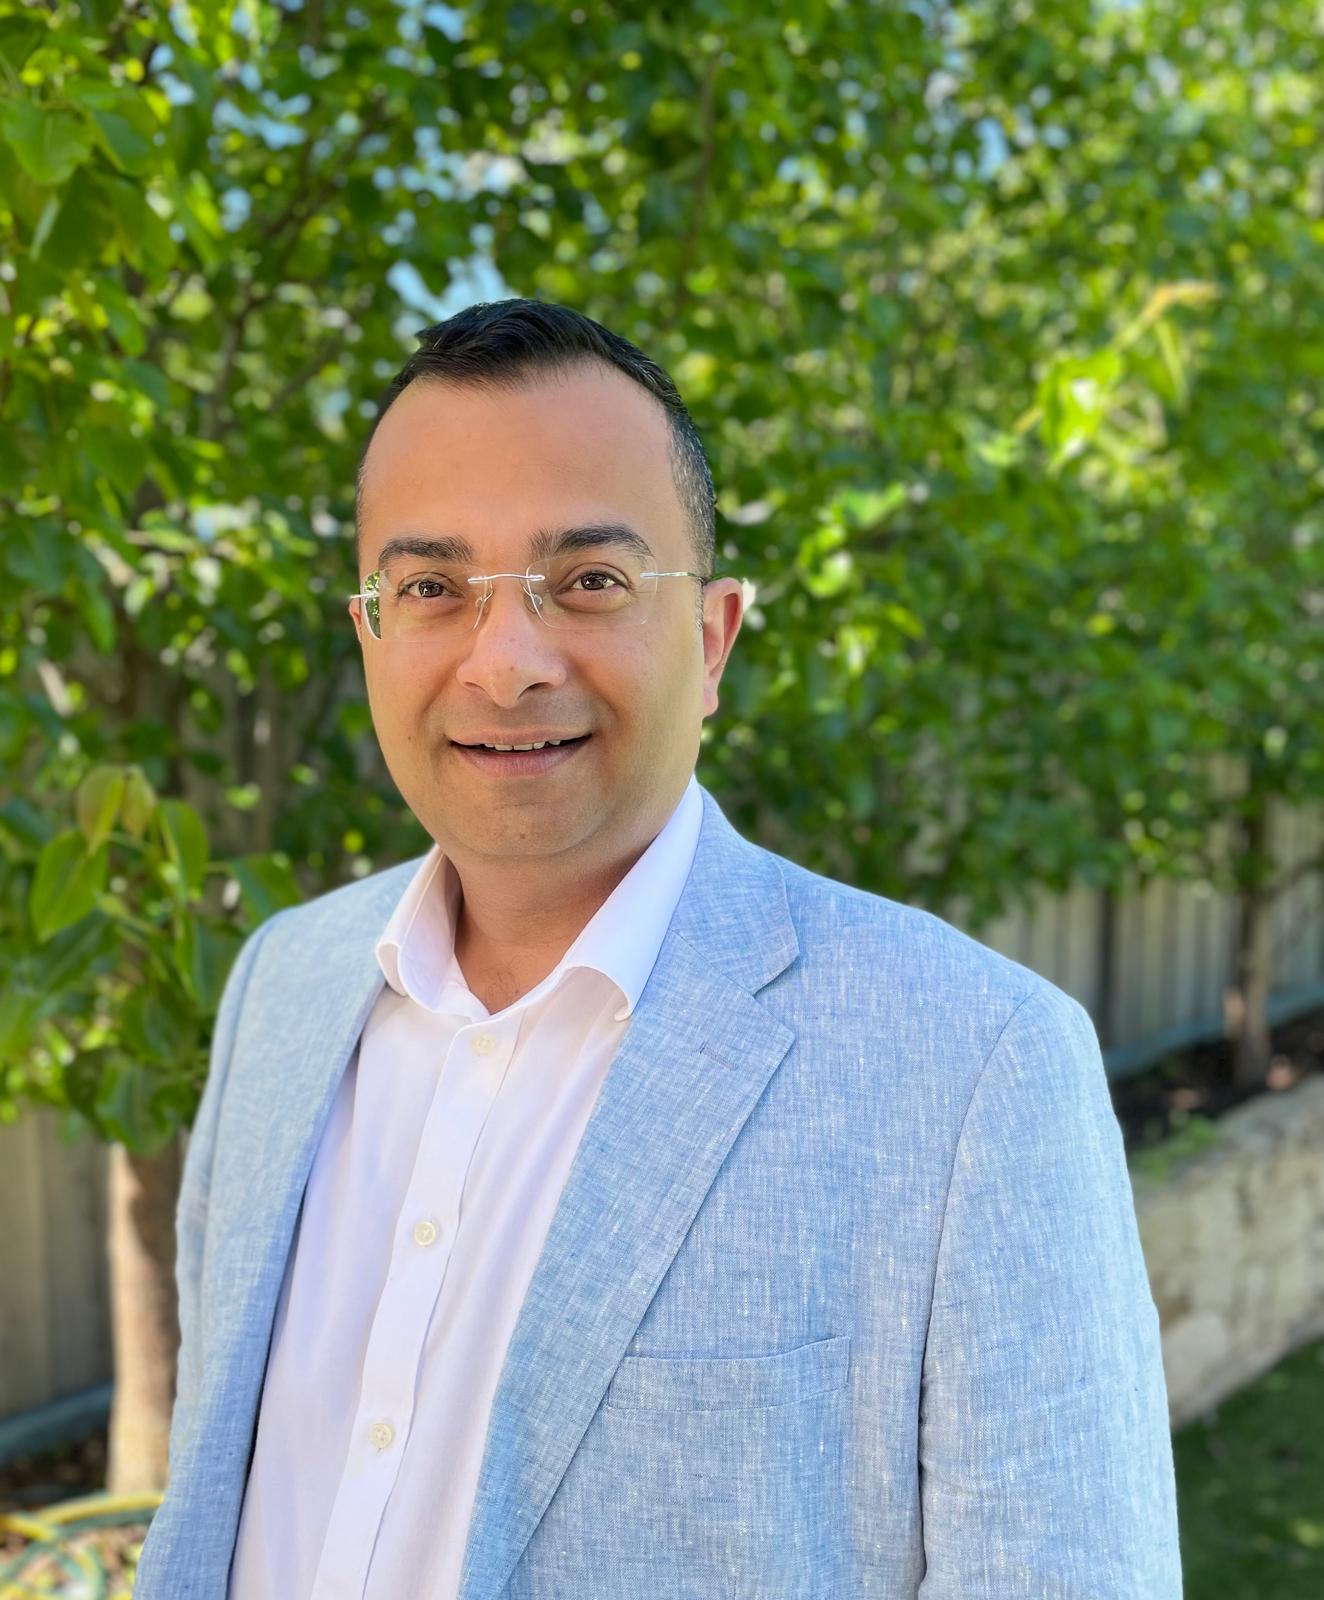
Brendan Singh
Brendan Singh is the Director and Mortgage Broker behind Loans Cart — 20 years in business development and partnerships, a panel of 30+ lenders, and advice delivered in English, Hindi, and Punjabi.
Based in Mount Waverley, South-East Melbourne, with offices in Bentleigh East and Truganina.
View Brendan's profile and credentialsTalk to a Broker — No Obligation
Book a chat with Brendan. We'll look at your situation and give you clear advice on your options — at no cost to you.
Brendan Singh is a Credit Representative (Credit Rep No. 575816) of BLSSA Pty Ltd ACL 391209. ABN 45 601 426 582